On November 11, 2026, at 20:29 CST, PANews published a TechFlow compilation of a Binance Research note by Kim Lim and Jasper Jin. The note asks why institutional crypto demand has scaled through passive spot funds while active crypto hedge funds have stayed small. The figures below are those in that compilation. They are a platform snapshot and a set of interviews, not a market-wide audit of reserves, liabilities, or legal title.
Two channels, and a different obligation behind each
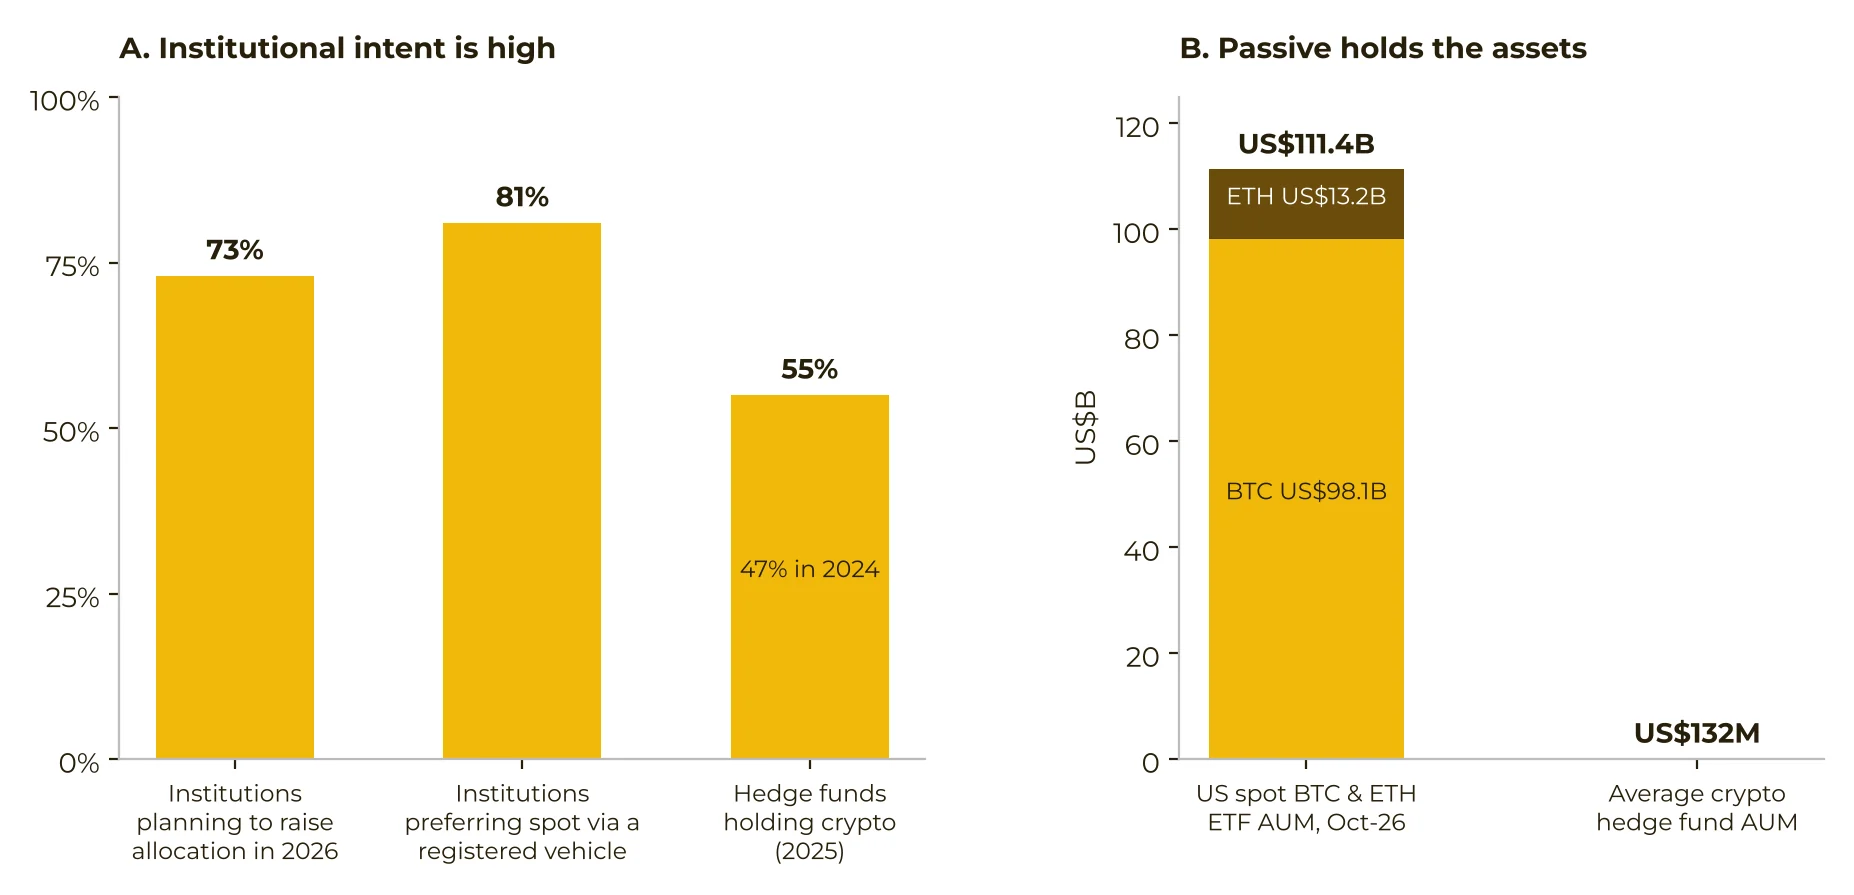
Binance Research puts combined assets in US spot Bitcoin and Ethereum ETFs at about $111 billion at the end of October 2026. It puts average assets of crypto hedge funds at $132 million, with 91 percent of those funds under $1 billion.
The report’s account of the gap starts with packaging, not with a claim that active managers lack skill. It says ETFs scaled because they offered an institutional wrapper: custody, audit, daily net-asset-value calculation, and reporting institutions already use. Active crypto strategies, it argues, have not offered the same degree of institutional integration. That explanation does not establish the solvency of any issuer, the segregation of any wallet, or whether reserves cover liabilities. A published asset figure is not a statement of who owns the coins or who is owed what.
The same caution shows up in position size. Among traditional hedge funds that hold crypto, more than half allocated less than 2 percent of total assets. The note separately says 60 percent of institutions planned to raise exposure above 2 percent within a year. On this account, limited size reflects the limits of the existing investment infrastructure, not a lack of interest.
Stated demand mostly used the passive route
The compilation cites a 2026 EY-Parthenon and Coinbase joint survey in which 73 percent of institutions planned to increase their digital-asset allocation this year. It cites an AIMA and PwC report finding that 55 percent of traditional hedge funds held crypto assets, up from 47 percent in 2024.
Binance Research says most of that demand has gone into passive vehicles. Among the surveyed institutions in its account, 81 percent preferred registered, compliant products for spot exposure. The accompanying chart is sourced to the EY-Parthenon and Coinbase survey of March 2026, the AIMA and PwC 2025 global crypto hedge fund report, a State Street digital-asset survey of October 2025, SoSoValue, and Binance Research, as of October 31, 2026. The prose does not isolate a separate State Street statistic.
Discovery is still mostly informal
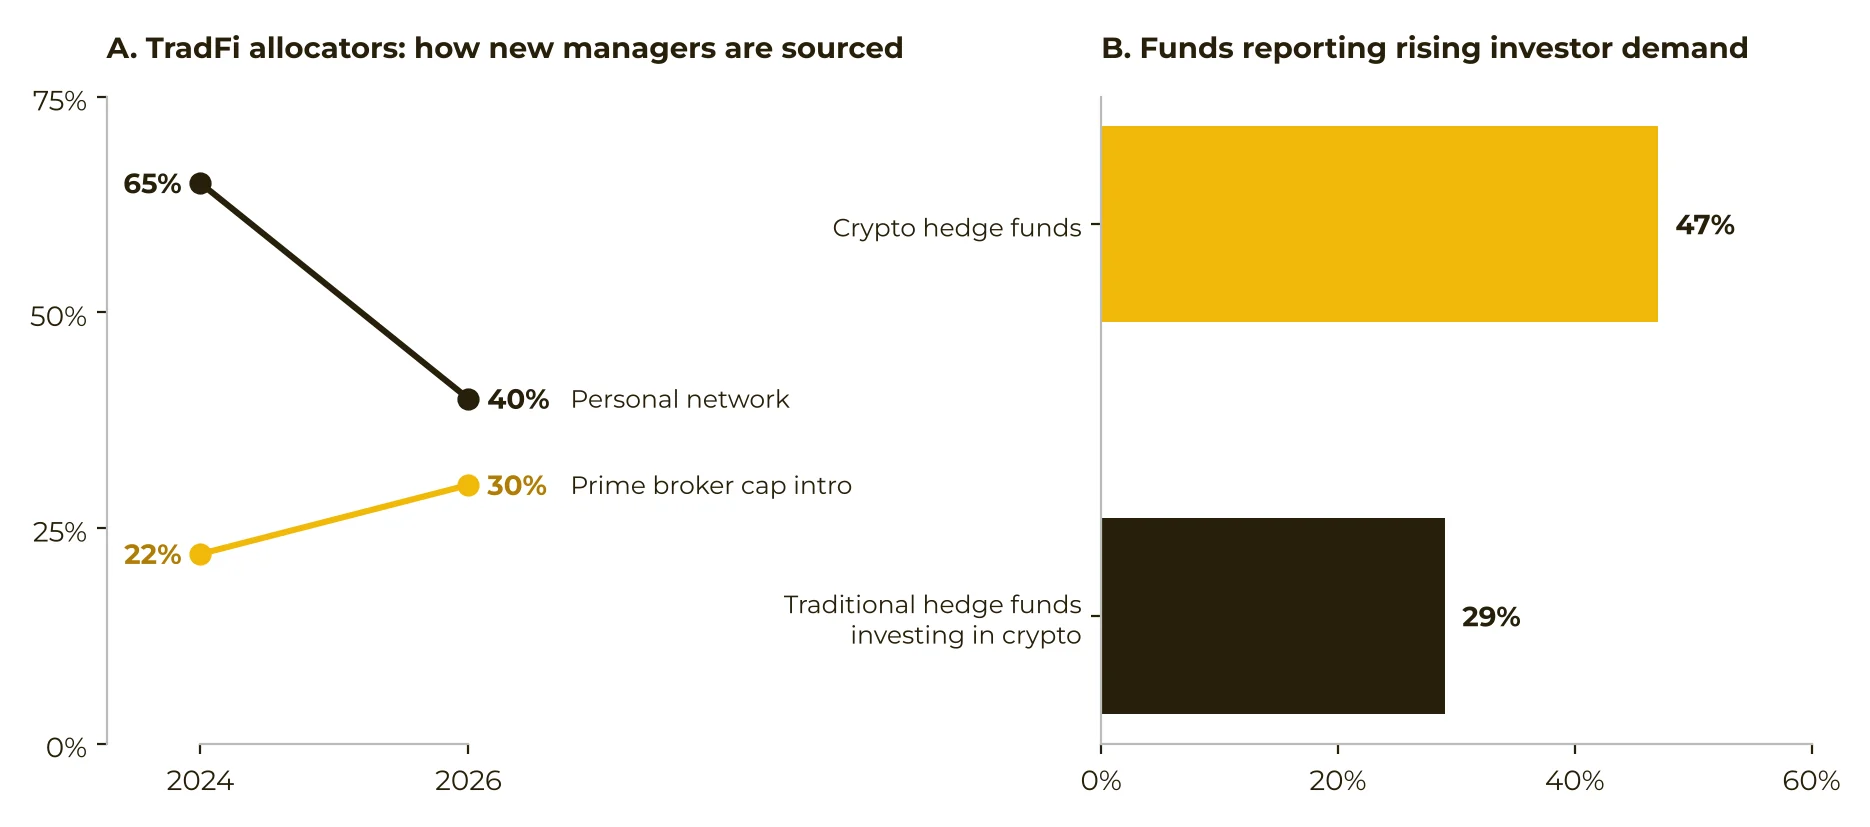
The authors argue that the constraint is discovery and verification, not a shortage of managers. They cite an AIMA and Marex survey: allocator reliance on personal networks fell from 65 percent in 2024 to 40 percent in 2026, while use of prime-broker capital introduction rose from 22 percent to 30 percent.
Crypto allocation, they write, still depends heavily on Telegram groups, offline conferences, and personal referrals. Without a shared performance disclosure and benchmark, investors cannot compare managers on the same terms. Institutions also have difficulty checking the audited financial statements, custody arrangements, and service-provider credentials the note says they now require.
The friction binds both sides. Forty-seven percent of crypto hedge funds said investor demand was rising, compared with 29 percent of traditional hedge funds involved in crypto. Family offices and high-net-worth individuals remained the main sources of capital. Only one-fifth of crypto hedge funds listed pensions, endowments, or sovereign wealth funds as a primary investor type, up from one-ninth a year earlier.
What Capital Connect showed through October 31, 2026
Capital Connect is described in the note as Binance’s regulated platform for discovering and allocating to crypto funds, set up to supply the distribution layer the authors say is missing. That is Binance Research’s description of its own venue. Strategies on the platform must disclose publicly, and results are measured on one standard. The update uses a snapshot through October 31, 2026, and adds direct interviews with allocators and managers for the first time. It is not an industry census. A larger share of platform assets is not evidence that a strategy is safer, audited, or that client obligations are collateralized.
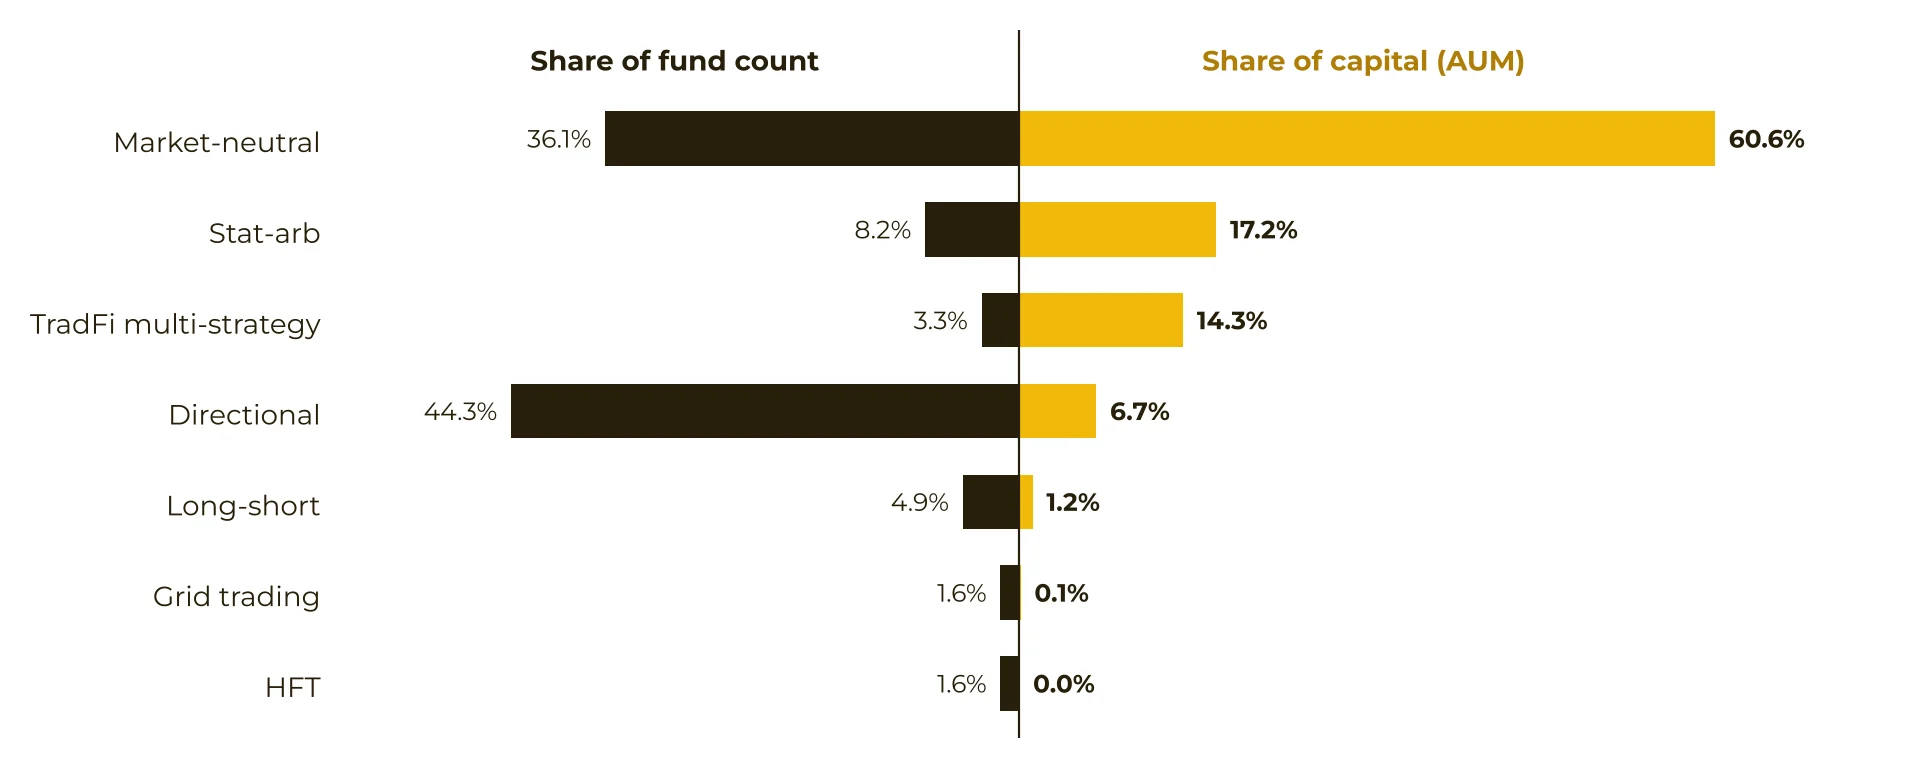
By count, directional strategies were the largest group, at 44.3 percent of funds, but they held 6.7 percent of platform assets. Market-neutral, statistical-arbitrage, and traditional-finance-style multi-strategy funds together held 92.1 percent of assets under management. Neutral strategies were under half of funds by number. Multi-strategy funds alone accounted for 14.3 percent. The average ticket in neutral strategies was about 11 times the average directional ticket.
Market-neutral participation had risen for two consecutive months and was up 30 percent since May. Statistical-arbitrage participation had more than doubled over the same period and stayed stable through October. The authors’ reading is that product supply and allocator demand point in opposite directions: many long-tail managers offer directional products, while platform capital concentrates in hedged strategies. The discovery layer, they say, makes that preference visible rather than creating it.
The note says its core conclusion still held in a month when Bitcoin fell 7 percent: hedged strategies remained dominant, coin-denominated mandates still produced the largest single tickets, and directional capital was waiting for a clearer recovery signal.
Two mandates, and what October did not prove
The compilation describes two mandate styles that were both growing, then uses October’s decline as a stress check.
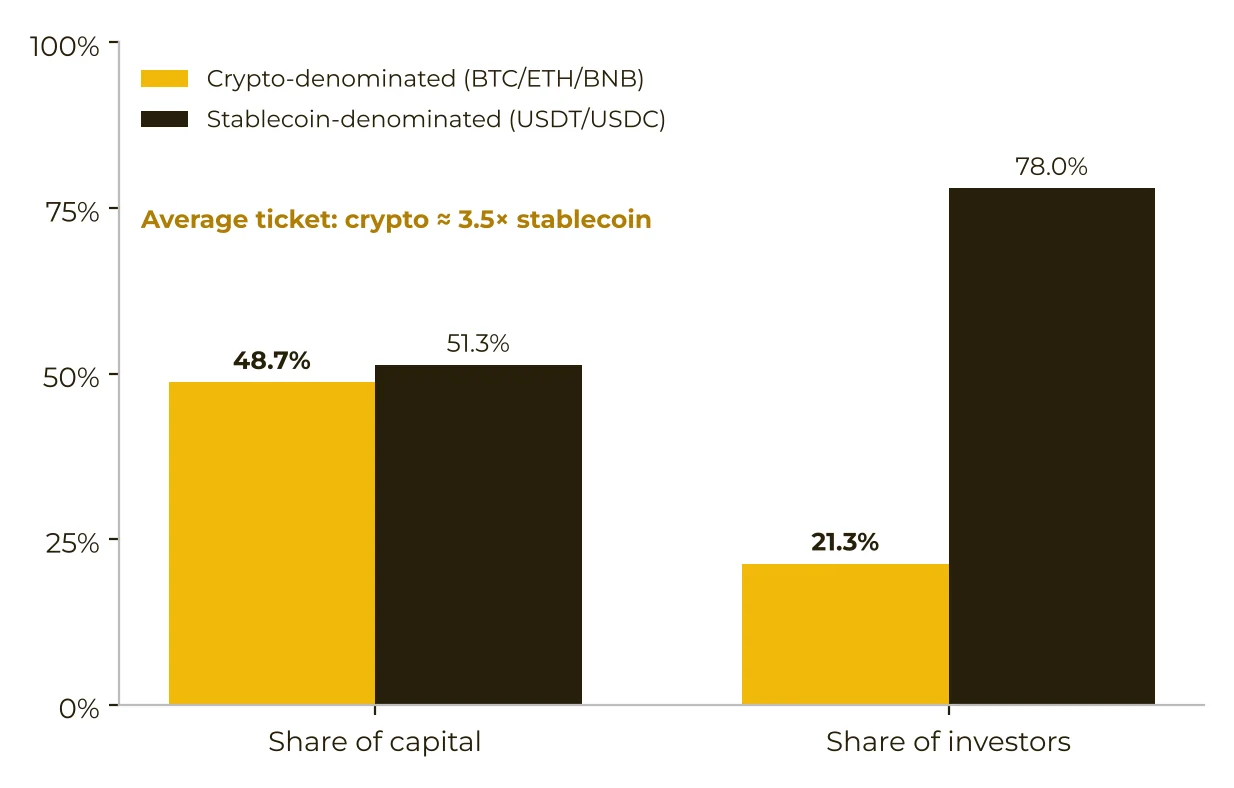
In the crypto-native style, 48.7 percent of platform capital sat in funds denominated in BTC, ETH, or BNB. Those funds had about one-fifth of the investors, but the average ticket was about 3.5 times that of stablecoin-denominated funds. Allocators kept the underlying coin exposure and outsourced the hedge. During October, coin-denominated physical holdings stayed stable, and the decline in dollar-measured assets mainly followed the bitcoin price. The note does not identify the custodian, the segregation terms, or who would owe what if a manager, venue, or counterparty failed. A stable coin balance is not a reserve-versus-liability statement and does not show legal ownership.
In the convergent style, traditional multi-strategy funds remained the third-largest strategy by capital, at 14.3 percent. Investor participation in that strategy fell 14 percent month over month in October, from 21 people to 18. Binance Research treats this as selectivity in a maturing market, not a reversal: a familiar product structure draws institutions in, and some allocators still stepped back even where the note describes results as steady.
Directional participation recovered, with a wide spread
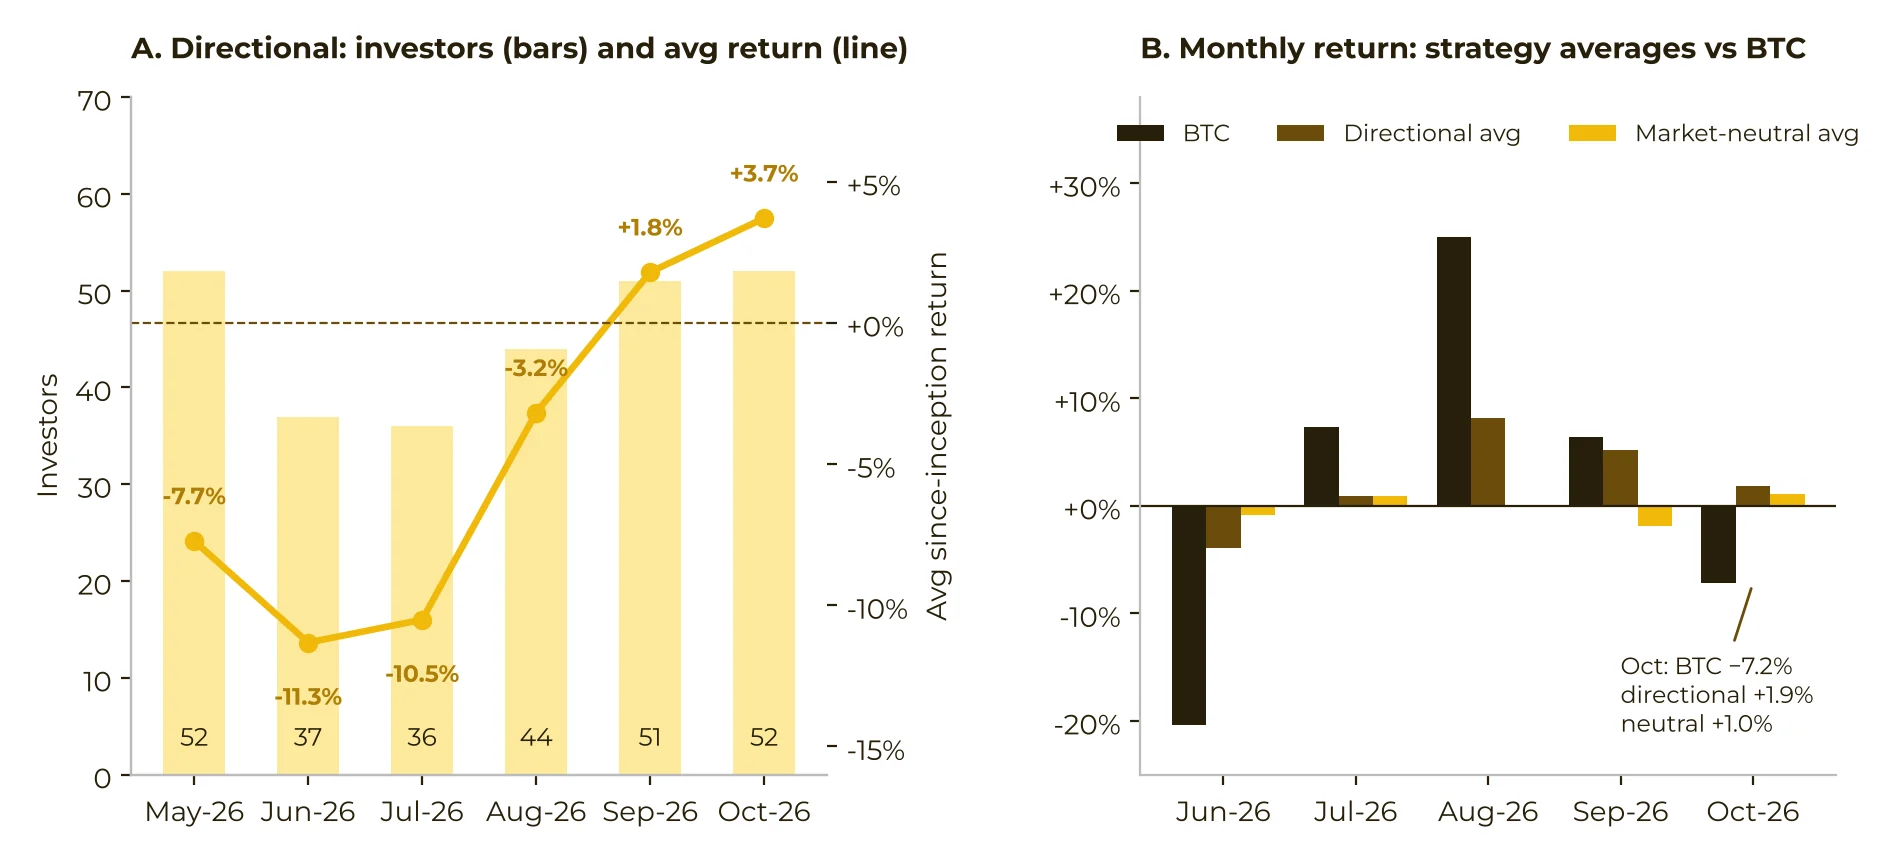
Directional investor counts fell sharply after returns bottomed in June, reached a low of 36 in July, and recovered to 52 in October, the May level. The average since-inception return of directional funds improved from −11 percent in June to +3.7 percent in October.
October was described as the first live test of that recovery. Bitcoin fell 7.2 percent in the month, while directional funds still averaged +1.9 percent and market-neutral funds averaged +1.0 percent. Interviews showed the pattern the authors describe: allocators generally cut directional exposure during drawdowns and add it back after volatility and liquidity settle.
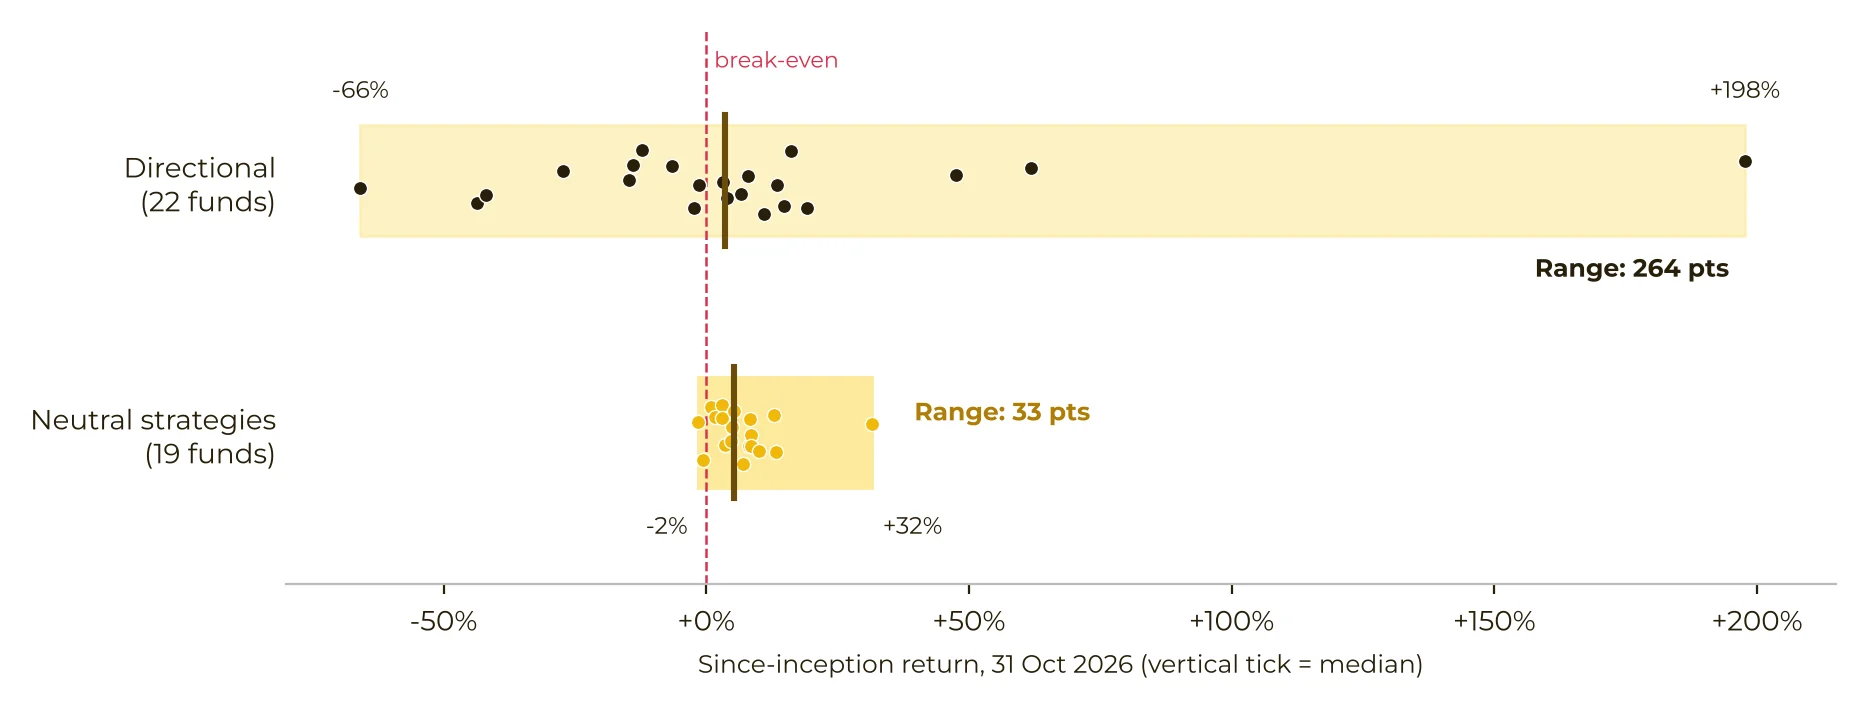
Dispersion is the constraint the averages hide. The gap between the best and worst directional funds was about eight times the gap among neutral strategies. The directional median was around +4 percent, and only 55 percent of directional funds were positive. Nine in ten neutral funds were positive. The top quarter of directional funds averaged +69 percent since inception. Allocators told the researchers they would still pay for alpha of that scale if drawdowns stayed controlled. Those are reported results and interview statements, not a forecast.
The chart notes say strategy returns are a simple average of fund net asset values, using Binance BTC/USDT for the bitcoin series. The dispersion comparison excludes dormant funds and funds managing less than $1,000. In that comparison, “neutral” covers market-neutral, statistical arbitrage, and traditional multi-strategy.
Interviews put safety and verification ahead of the return
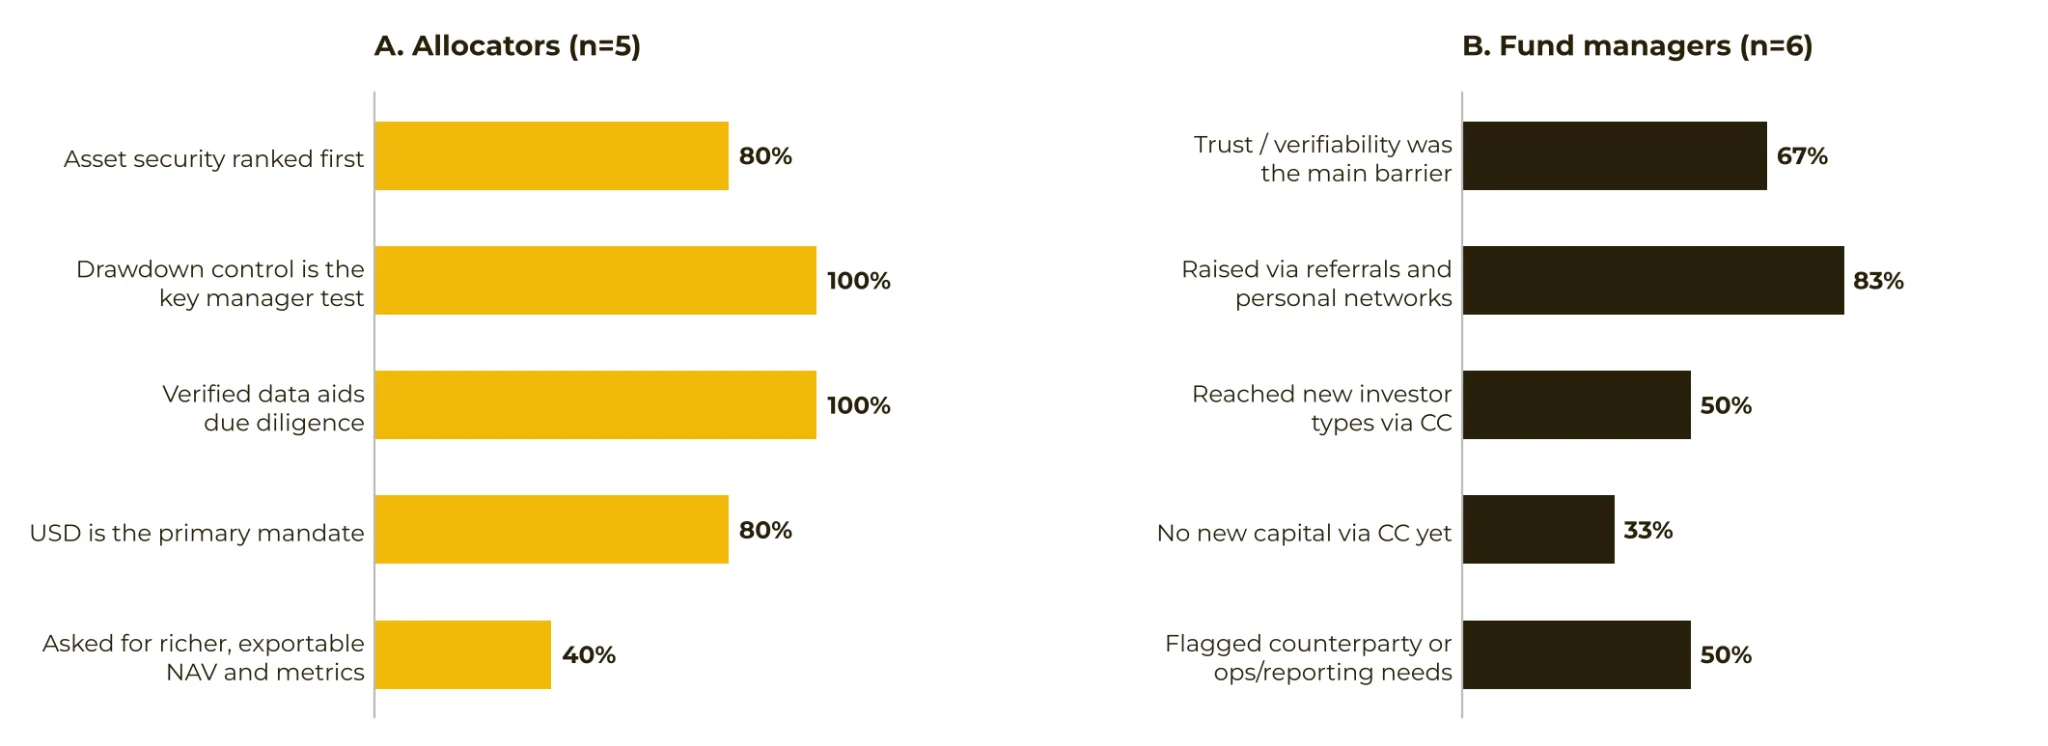
Interviews with Capital Connect allocators and the trading teams running funds were conducted from October 29 to November 1, 2026. Eighty percent of allocator respondents ranked asset safety first, above track record and institutional reputation. Every allocator interviewed said verified data from inside an exchange could significantly strengthen due diligence. They also said they weighed drawdown control more than a high reported return.
Managers described the fundraising obstacle as trust cost, not an insufficiently bright return. Past performance was hard to cross-check. KYC, anti-money-laundering, and counterparty compliance reviews slowed fundraising, so most capital still depended on personal referrals. After listing, some managers said they could reach a wider investor set, compliant institutions, and pools assembled from smaller tickets.
Both sides, in the authors’ summary, treat verifiability as the door to trust and operating infrastructure as what widens the path. That does not establish what a diligence file often gets asked to prove. Exchange-internal data can show activity visible to that exchange. It does not establish legal ownership, a complete liability ledger, an independent audit, solvency, or customer protections. Ranking asset safety first is a stated preference, not evidence that safety was delivered.
What the authors say the note is not
Binance Research says the report is not a forecast, investment advice, or an offer or solicitation to buy or sell any product, cryptoasset, or strategy. It says the views are for industry understanding, are not a formal legal opinion or Binance’s position, are current only as of the dates given, and may change. It says the information comes from proprietary and non-proprietary sources it considers reliable, may be incomplete, and is not guaranteed accurate, and that forward-looking statements may not be realized.
Source: panewslab.com (originally published 2026-11-11 20:29 UTC+8)